
Launch Date: July 5, 2006
Withdrawal Date: 2010 (Regulatory Withdrawal)
Type: Unit Linked Pension Plan (ULPP)
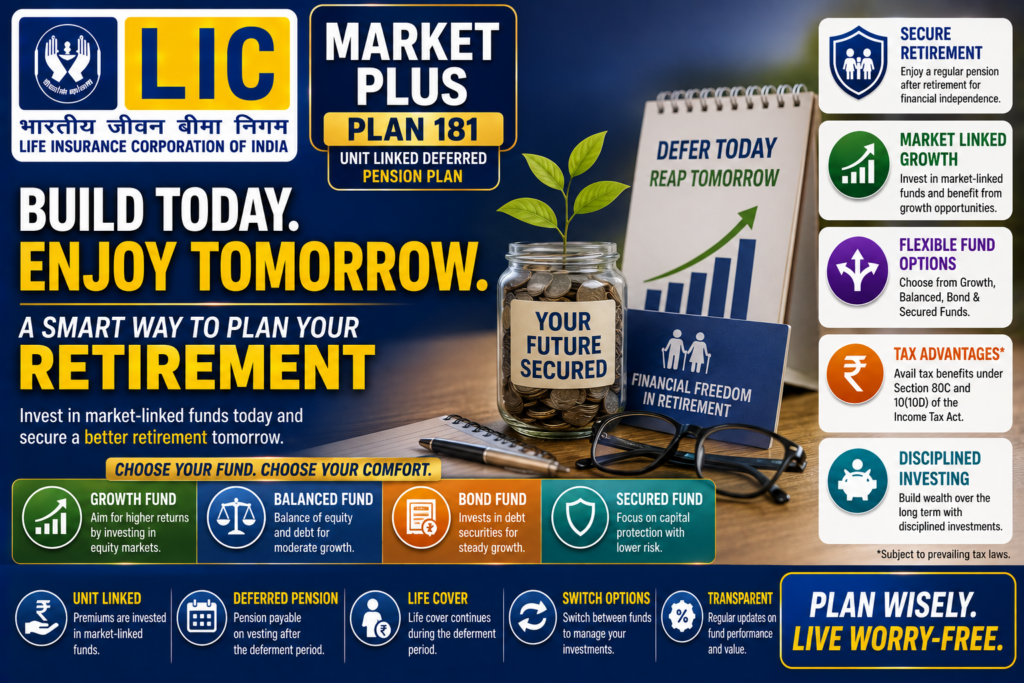
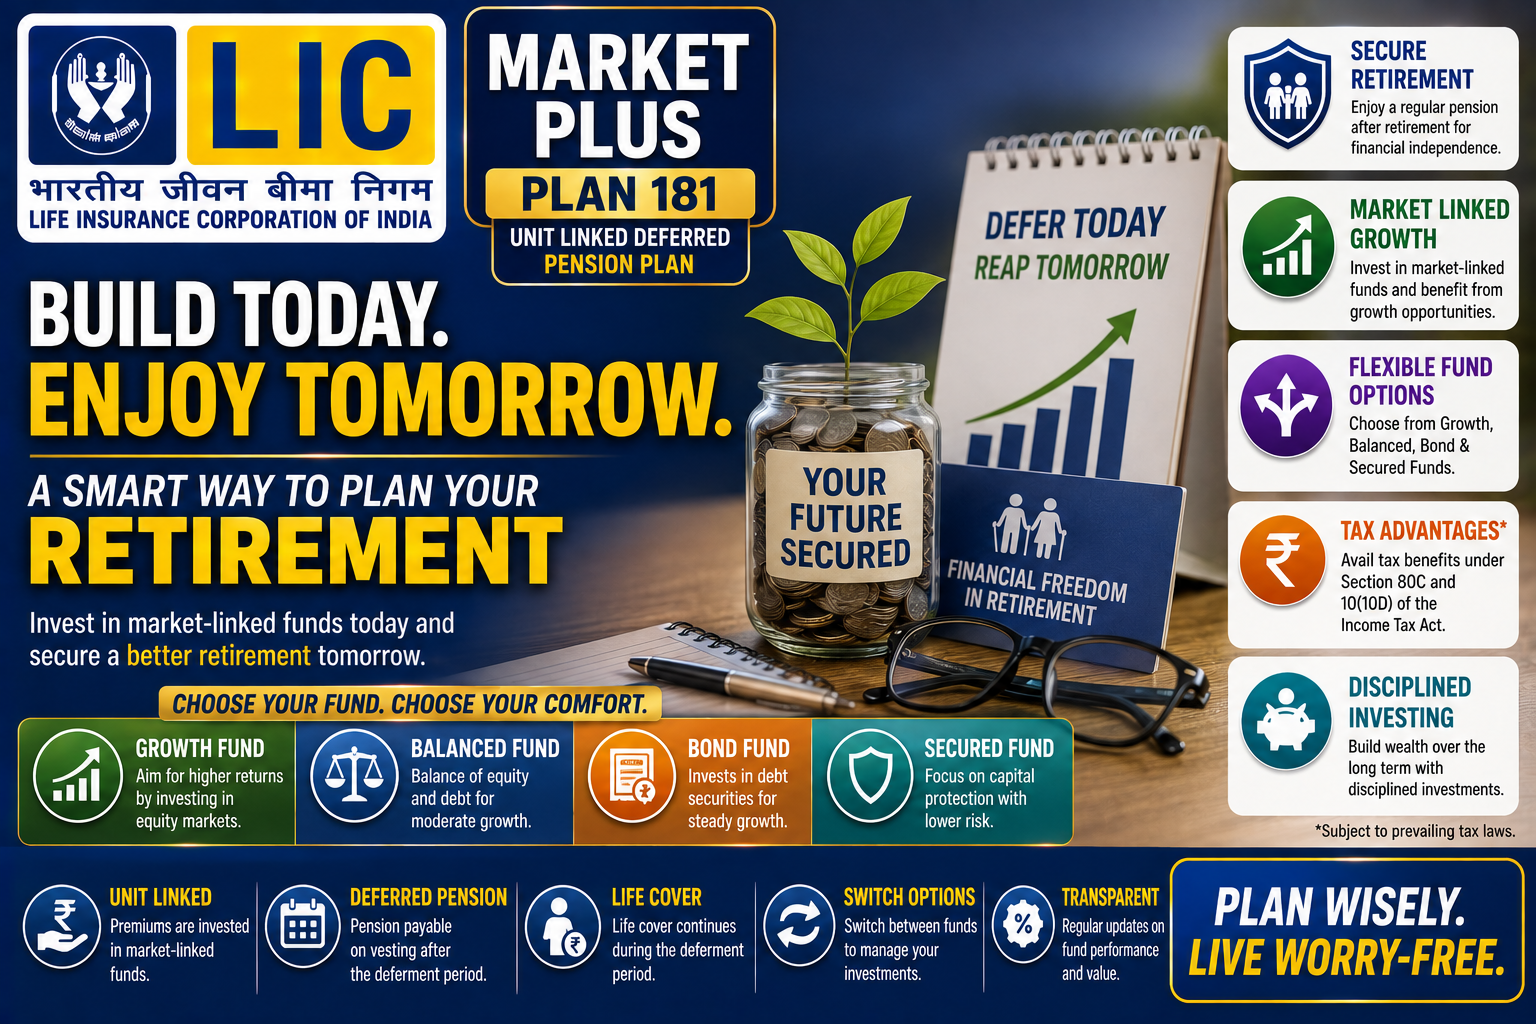
Planning for retirement requires a combination of long-term savings and financial protection. LIC Market Plus Plan 181 was one of the older unit-linked pension products introduced by the Life Insurance Corporation of India (LIC). It was designed to help policyholders build a retirement corpus through market-linked funds and use that accumulated amount to generate pension income later.
Although the plan is no longer available for new purchases, existing policyholders can still use an LIC Market Plus Plan 181 Calculator to understand their fund value, investment growth, charges, death benefits, and expected retirement corpus.
What is LIC Market Plus Plan 181?
LIC Market Plus Plan 181 was a unit-linked deferred pension plan. Under this type of plan, premiums were allocated toward market-linked units after applicable charges.
The plan provided different fund options, such as Growth, Balanced, Bond, and Secured Funds, allowing policyholders to select an investment option according to their preferred level of risk.
In simple terms:
- It is a unit-linked pension plan.
- It is designed as a deferred pension product.
- Premiums are invested in selected market-linked funds.
- The value of the policy depends on the number of units and the applicable NAV.
- At vesting, the accumulated fund can be used to purchase an annuity or receive the permitted lump-sum portion.
Launch and Withdrawal Date
According to the information provided, LIC Market Plus Plan 181 was:
- Launch Date: 5 July 2006
- Withdrawal Date: 1 April 2008
Since the plan was withdrawn from new sales, it is not possible to purchase a fresh Market Plus 181 policy today. However, existing policyholders can continue to manage their policies according to the original terms and track their accumulated fund value.
LIC Market Plus Plan 181 Eligibility and Basic Details
| Parameter | Details |
|---|---|
| Plan Number | 181 – Market Plus |
| Plan Type | Unit-linked deferred pension plan |
| Minimum Entry Age | 18 years completed |
| Maximum Entry Age | 70 years without life cover; 65 years with life cover |
| Minimum Vesting Age | 40 years |
| Maximum Vesting Age | 75 years |
| Minimum Deferment Period | 5 years |
| Premium Modes | Yearly, Half-yearly, Quarterly, Single Premium |
| Minimum Regular Premium | ₹5,000 per year |
| Minimum Single Premium | ₹10,000 |
| Maximum Sum Assured – Regular | 20 times annualised premium |
| Maximum Sum Assured – Single | Up to the single premium amount |
These details are also important when using a Market Plus Plan 181 Calculator, as the calculation may require information such as age, premium, payment mode, deferment period, and selected fund.
How Does LIC Market Plus Plan 181 Work?
The working of the plan can broadly be understood in three stages.
1. Premium Payment and Unit Allocation
When a premium is paid, applicable allocation charges are deducted and the remaining amount is invested in the selected unit fund.
LIC then allocates units according to the applicable Net Asset Value (NAV).
For example, if a policyholder pays a single premium of ₹1,00,000 and ₹3,300 is deducted as an allocation charge, ₹96,700 may be allocated to the unit fund.
If the applicable NAV is ₹10 per unit:
Units allocated = ₹96,700 ÷ ₹10 = approximately 9,670 units
The actual calculation depends on the applicable charges and NAV.
2. Policy Charges
Certain policy-related charges are recovered by cancelling units from the policyholder’s unit account.
These may include:
- Premium allocation charges
- Policy administration charges
- Mortality charges where life cover is selected
- Accident benefit charges, where applicable
- Applicable service-related taxes or charges
Therefore, the number of units can reduce as charges are deducted from the policy.
3. Fund Value and NAV
The value of the policy is linked to the NAV of the selected fund.
The basic calculation is:
LIC Market Plus 181 offered different investment funds, including:
- Growth Fund – Higher exposure to equity and comparatively higher market risk.
- Balanced Fund – Combination of equity and debt investments.
- Bond Fund – Primarily focused on debt-oriented investments.
- Secured Fund – More conservative investment approach.
Because the fund value changes with NAV, historical NAV information and the correct policy dates are important when estimating the value of an existing policy.
Market Plus 181 Maturity / Vesting Benefits
When the policy reaches its vesting date and the applicable conditions are satisfied, the policyholder receives the fund value accumulated in the policy.
The accumulated amount can then be used according to the available pension options.
Lump-Sum Commutation
A policyholder can commute up to one-third of the fund value as a lump sum.
The remaining portion is used for purchasing an immediate annuity or pension.
A calculator can therefore help estimate:
- Total fund value at vesting
- Permitted lump-sum amount
- Remaining amount for annuity purchase
- Approximate pension based on applicable annuity rates
Pension from Another Insurer
The accumulated fund may also be used to purchase an annuity from another life insurer, subject to the applicable policy conditions.
The policyholder is required to inform LIC within the prescribed period before vesting if this option is selected.
This can be useful for policyholders who want to compare available annuity options.
Death Benefit Under LIC Market Plus Plan 181
The death benefit depends on whether life cover was selected under the policy.
Policy With Life Cover
If the life assured dies during the deferment period, the death benefit is generally based on:
Sum Assured + Fund Value
The applicable benefit can be taken according to the options permitted under the policy.
Policy Without Life Cover
Where the policy does not include life cover, the death benefit is based on the fund value of the units.
In Case of a Lapsed Policy
Where a policy has lapsed and the required minimum premium period has not been completed, the applicable death benefit is determined according to the policy’s specific conditions.
Therefore, existing policyholders should check their policy documents before relying on an estimated death-benefit figure.
Accident Benefit Rider (DAB)
LIC Market Plus 181 also provided an option for an Accident Benefit Rider, commonly referred to as Double Accident Benefit (DAB), subject to the applicable terms.
The information provided includes:
- Standard additional premium: ₹0.50 per ₹1,000 of accident benefit sum assured per year
- Higher rate for certain high-risk occupations: ₹1 per ₹1,000
- Minimum accident benefit sum assured: ₹25,000
- Maximum accident benefit sum assured across policies: ₹50 lakh
If this rider is selected, the calculator can help show the additional premium and the increased protection available in the event of accidental death.
LIC Market Plus Plan 181 Calculator
Since Market Plus Plan 181 is a discontinued product, calculating its current or projected value can be difficult manually.
An LIC Market Plus Plan 181 Calculator can simplify the process by allowing existing policyholders to enter their policy details and estimate important figures.
Depending on the calculator, it can help estimate:
- Current or projected fund value
- Number of units
- NAV-based growth
- Applicable charges
- Death benefit
- Vesting corpus
- Lump-sum amount
- Approximate pension
- Impact of different fund options
Information Required for the Calculator
For a more useful calculation, users may need to enter:
- Age at entry
- Current age
- Vesting age or policy term
- Premium amount
- Premium payment mode
- Selected fund
- Life cover details
- Accident benefit rider details
- Applicable charges
- Expected or historical NAV
These inputs help the calculator provide a more meaningful illustration of the policy.
How to Use LIC Market Plus Plan 181 Calculator
Using the calculator is generally straightforward.
Step 1: Enter Premium Payment Mode
Select the applicable mode, such as:
- Yearly
- Half-yearly
- Quarterly
- Single Premium
Step 2: Enter Premium Amount
Enter the premium amount paid under your policy.
Step 3: Enter Deferment / Policy Term
Enter the relevant deferment period or policy term according to your policy document.
Step 4: Select Fund
Choose the applicable fund, such as Growth, Balanced, Bond, or Secured.
Step 5: Add Life Cover Details
If your policy includes life cover, enter the relevant sum assured.
Step 6: Calculate
The calculator can then provide an illustration of the policy value, accumulated corpus, and other applicable benefits.
Example Calculation
Consider an example where:
- Entry age: 35 years
- Annual premium: ₹50,000
- Premium mode: Yearly
- Policy term: 20 years
- Fund: Growth Fund
- Accident benefit rider: Not selected
The calculator can estimate the initial units after applicable allocation charges and then account for ongoing policy charges.
As the NAV changes over time, the value of the units also changes.
At the end of the 20-year period, the calculator can provide an illustration of:
- Total accumulated fund value
- One-third potential lump-sum amount
- Remaining amount available for annuity
- Estimated pension based on applicable assumptions
Actual results will depend on the policy’s historical NAV, charges, premium payments, and other applicable terms.
Why Use an LIC Market Plus 181 Calculator?
A calculator can make it easier for existing policyholders to understand an old unit-linked pension policy.
Track Fund Growth
You can compare the unit value and NAV over different periods to understand how the investment has performed.
Compare Fund Options
The calculator can help illustrate differences between Growth, Balanced, Bond, and Secured Funds.
Understand Charges
Since charges can reduce the number of units, including them in the calculation gives a better picture of the actual fund value.
Plan Retirement Income
Knowing the estimated vesting corpus can help you understand how much may be available for lump-sum withdrawal and annuity purchase.
Compare Different Scenarios
You can change variables such as premium, term, fund choice, or other assumptions to understand how the estimated outcome changes.
What Happens If Premium Payments Stop?
If premiums are not paid within the applicable grace period, the policy may lapse according to the policy conditions.
Where the required number of premiums has already been paid, certain continuation provisions may apply. The specific treatment depends on the policy status and original terms.
Therefore, existing policyholders should check their policy documents before deciding whether to discontinue premium payments.
Frequently Asked Questions
What is LIC Market Plus Plan 181?
LIC Market Plus Plan 181 is a unit-linked deferred pension plan introduced by LIC in 2006. Premiums are invested in selected market-linked funds and the accumulated fund can be used for retirement benefits at vesting.
Can I purchase LIC Market Plus Plan 181 today?
No. The plan was withdrawn from new sales on 1 April 2008, so it is available only to existing policyholders.
What was the minimum premium?
The minimum regular premium was ₹5,000 per year, while the minimum single premium was ₹10,000.
Which funds were available?
The plan included options such as Growth, Balanced, Bond, and Secured Funds.
Is there a loan facility under Market Plus 181?
No. LIC Market Plus Plan 181 does not provide a loan facility.
What happens at vesting?
At vesting, the policyholder receives the applicable fund value and can use it according to the permitted pension and commutation options.
Can I receive the entire fund value as cash?
The plan provides for commutation of up to one-third of the fund value, with the balance generally used for purchasing an annuity, subject to the applicable rules.
Conclusion
LIC Market Plus Plan 181 was a unit-linked deferred pension product launched on 5 July 2006 and subsequently withdrawn from new sales on 1 April 2008. Since it is a discontinued plan, it is relevant mainly to existing policyholders.
The plan allowed policyholders to invest through different funds, including Growth, Balanced, Bond, and Secured options, while also providing pension-related benefits at vesting.
An LIC Market Plus Plan 181 Calculator can make it easier to understand the policy by estimating fund value, NAV-based growth, charges, death benefits, vesting corpus, lump-sum eligibility, and potential pension amounts.
For an existing policyholder, such a calculator can be a useful way to get a clearer picture of how the policy has performed and what may be available at the time of vesting.
Note: All images and videos used on this website are sourced from Google or YouTube. If you have any issues regarding any image or video, please contact us via email through our official website.
If you find any problem with this post or wish to request its removal, please contact us through:
https://licpolicycalculator.in/contact-us

Comments 0